How to File a Property Damage Insurance Claim in Oklahoma: Step by Step
When your home or business is damaged by water, fire, wind or hail, the insurance claim can feel as stressful as the damage itself. Knowing the steps ahead of time makes it much easier.
This is general guidance for Oklahoma property owners. Every policy is different, so always read your own policy and ask your insurer or agent about anything that is unclear.
Step 1: Make the property safe and prevent more damage
Stop the water, tarp the roof (storm damage help in Lawton), board up openings and move valuables out of harm’s way. Policies generally expect you to take reasonable steps to prevent additional damage. Keep receipts for anything you spend.
Step 2: Document everything
- Photos and video of every affected room, wide shots and close-ups
- The cause of the damage, if visible — the burst pipe, the hole in the roof
- Damaged belongings before they are thrown away, with brand and model where possible
- Dates and times of the event and of every call you make
Step 3: Notify your insurer promptly
Call your insurer or agent, or file online, as soon as you can. Ask for your claim number, the adjuster’s contact details, what your policy covers for this type of loss, your deductible, and whether you have coverage for additional living expenses.
Step 4: Get a professional assessment
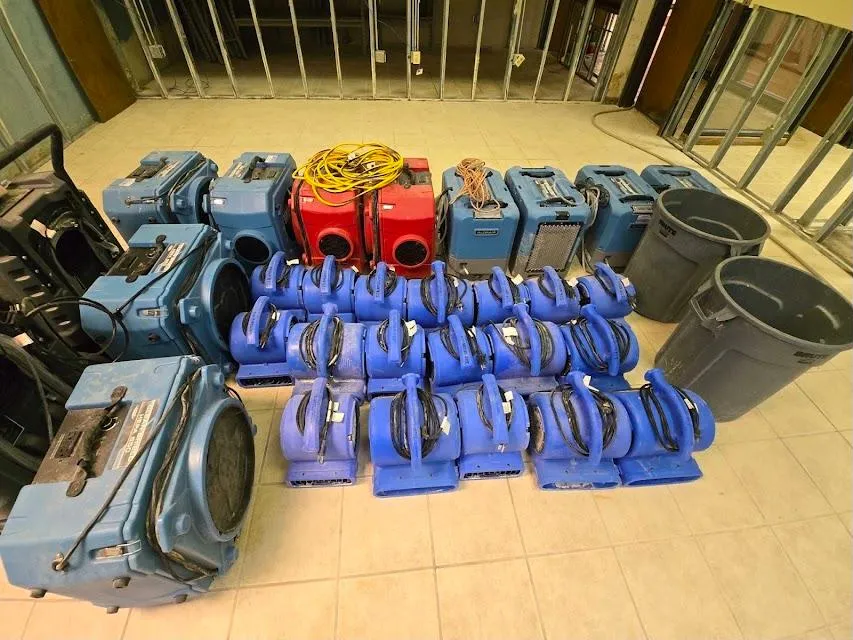
A restoration contractor can document moisture readings, affected materials and a detailed scope of work. That documentation helps the adjuster understand the full extent of the damage, including what is hidden inside walls and under floors. Learn how ICR handles insurance restoration.
Step 5: Meet the adjuster
Be present for the inspection if you can, and have your photos, receipts and contractor documentation ready. It helps to have your contractor there too, so the scope can be discussed in detail.
Step 6: Review the estimate and settlement
Compare the insurer’s estimate with your contractor’s scope. If something was missed, ask for a supplement with supporting documentation. Ask how payments will be issued — mortgage companies are sometimes named on checks for structural repairs.
Common mistakes to avoid
- Waiting too long to report the damage
- Throwing out damaged items before they are documented
- Starting permanent repairs before the adjuster has seen the damage, unless your insurer approves it
- Signing contracts with door-to-door contractors you have not checked out
- Assuming the first estimate is final
Where to get help
If you have questions about how your claim is being handled, the Oklahoma Insurance Department offers consumer assistance. Some property owners with large or disputed claims also work with a licensed public adjuster or an attorney.
Need help in Lawton right now?
ICR crews respond 24/7 across Lawton, Fort Sill and Comanche County.
Frequently Asked Questions
Can my restoration company talk to my insurance adjuster?
Yes. ICR provides documentation and communicates with your adjuster about the scope of work. Decisions about coverage and payment are made by your insurance company.
Do I have to use the contractor my insurer recommends?
In general you can choose your own contractor, but check your policy and talk with your insurer about how it works for your claim.
This article is general information, not legal or insurance advice. Insurance Claim Restoration is a restoration contractor, not an insurance company; coverage decisions are made by your insurer under your specific policy.